Washington County's Helene recovery group has announced it will stop taking new requests on November 16 and close by December 31. If your home was damaged by Helene and you have not yet asked for help, the clock is now short. Here is how insurance and recovery aid fit together, and what to do before the deadline.
Recovery Aid Is Not the Same as Insurance
Long-term recovery groups are usually funded by donations and grants. They fill gaps, such as repairs your insurance did not pay for or costs for households with no coverage. They generally cannot replace a claim you are entitled to file with your insurer. Most groups will ask whether you filed a claim and what it paid, so keep those records handy.
Step 1: Review Your Claim Status
- Find your claim number and the date of loss.
- Ask your adjuster for the written estimate and any denial or partial-payment letter.
- Check your policy's deadline for filing or reopening a claim. Many policies require notice within a set period, and some storm-related claims have shorter windows.
Step 2: Understand Wind, Water and Flood
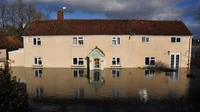
A standard homeowners policy typically covers wind damage, including trees falling on the house. Rising water from a river or overland flooding is generally excluded and requires separate flood insurance. Many Helene losses involved both, which is why some owners received partial payments. If a payment was lower than you expected, ask the insurer to explain which part of the loss was classified as which cause.
Step 3: Document What Is Still Unrepaired
Recovery groups look for specific, verified needs. Take dated photos, gather contractor estimates and keep receipts for temporary repairs. These also help if you need to supplement an insurance claim.
Step 4: Think About Next Year
- Flood insurance: Most flood policies have a waiting period, commonly 30 days, so do not wait for the next storm.
- Replacement cost: Rebuilding costs have climbed. Confirm your dwelling limit still matches today's cost to rebuild.
- Ordinance or law coverage: This can help pay for code upgrades required when rebuilding.
- Loss of use: Know how much temporary housing the policy pays for.
Buying or Selling a Storm-Affected Home
Buyers in flood-affected areas should ask about prior claims and check flood zone status before closing. Sellers should keep repair records. Lenders may require flood coverage in mapped zones, so get quotes early.
Talk to a Local Agent
Every property and policy is different. The team at All Seasons Insurance Group can review your coverage and explain your options. Call (865) 263-1400 or visit asigtn.com.
Buying or selling? Kings of Real Estate can help with the real estate side, and AnnieMac Home Mortgage can help with financing at (865) 518-6408.