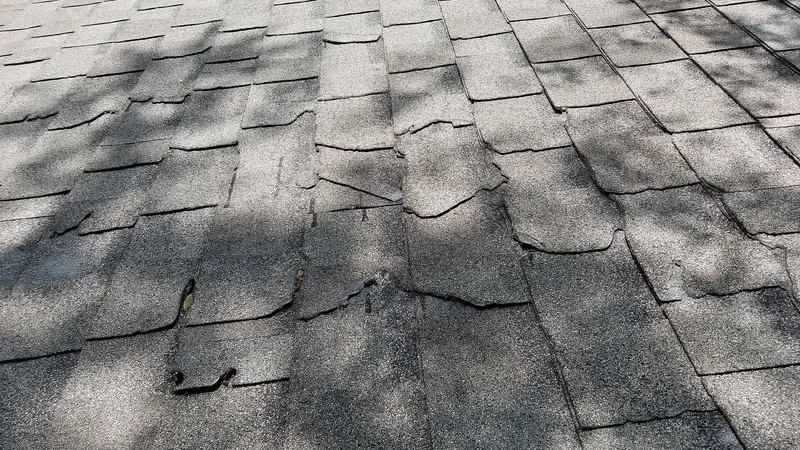
A fallen oak through the roof, a kitchen fire, or a hailstorm that takes the shingles and the gutters can push a Tennessee homeowners claim past $20,000 quickly. At that size, Tennessee Code § 56-7-125 requires the insurer to hand you a written statement of basic rights. Most people file it with the rest of the claim paperwork. It is worth reading first.
| Rule | What the statute says |
|---|---|
| When it applies | A personal lines fire or homeowners claim for structural damage estimated at $20,000 or more |
| What the insurer must provide | A written statement of basic rights under your policy |
| Repairs | Quality repair work; a contractor of your choice who works for you, not the insurer |
| Paperwork | Free copy of the policy on request; notice if a proof of loss is required |
| Contacts and estimate | Claim rep's name, phone, and address; a detailed estimate of scope and repair costs |
| After the first payment | Right to file supplemental claims |
| If talks stall | Complaint line at the Department: 1-800-342-4029 |
| Unfinished construction (§ 56-7-111) | On losses over $1,000, the general contractor on an uncompleted contract is named as a payee on the check |
Sources: Tennessee Code §§ 56-7-125 and 56-7-111.
When the $20,000 statement is required
The statute applies when a policyholder files a property claim under a personal lines fire or homeowners policy for structural damage with an estimated value at or above $20,000. Contents-only claims and smaller structural claims are outside the trigger. Once it applies, the insurer must provide a written statement setting out certain basic rights you have under the policy.
The eight rights the statement must list
- Quality repairs. The right to receive quality repair work to restore the damage.
- Your contractor. The right to have repairs made by a contractor of your choice. The statute is explicit that the contractor is hired by you and does not work for or at the direction of the insurance company.
- Your policy. A copy of the insurance policy, free of charge, on request.
- Proof of loss. To be told if you need to file a proof of loss.
- Who is handling it. The name, phone number, and address of the claim representative.
- The estimate. A detailed estimate of the scope of damage and the cost of repairs. If your contractor has questions about the insurer's estimate, you or your contractor should contact the claim representative directly.
- Supplements. The right to file supplemental claims as the need arises, which matters when hidden damage turns up after tear-off or demolition.
- A complaint. The right to file a complaint with the Department of Commerce and Insurance by calling 1-800-342-4029 if you cannot work out an agreement with the claim representative, agent, and company.
The step-by-step complaint process is here: How Tennesseans file an insurance complaint with TDCI’s Consumer Insurance Services.
What the statement does not do
The statement must also tell you that these requirements do not amend or replace any part of your policy, and that you should carefully read your policy, including its coverages, conditions, exclusions, and rights. In other words, the statement explains your rights in the claim process; the policy still decides what is covered and for how much. For how replacement cost and actual cash value change the check, see TDCI explains Actual Cash Value versus Replacement Cost for Tennessee homeowners.
Building or remodeling when the loss happens: § 56-7-111
A related statute covers homes with unfinished work. When an insured property loss over $1,000 occurs and there is an uncompleted construction or building contract, the insurer must name the general contractor on that contract as a payee on the draft to the owner. The statute says this applies regardless of whether the work performed or remaining is less than $25,000. Expect a two-party check, and plan for both signatures before funds move.
A practical checklist for a large claim
- Ask for the written statement if you have not received it once structural damage is estimated at $20,000 or more.
- Request a free copy of the full policy, including endorsements and the declarations page.
- Get the detailed estimate in writing and give it to your contractor before work starts.
- Keep a log of every call with the claim representative: date, name, and what was said.
- Read any roofing contract carefully before you sign: Tennessee homeowners can cancel a roofing contract within three business days after their insurer says the claim is not covered.
- If payment is slow or the estimate looks short, know the rules on claim handling: Tennessee law lists 15 unfair claims practices, including slow responses and unexplained claim denials. and Storm Claim Underpaid in Tennessee? Your Next Steps
Filing the claim itself, step by step: How to File a Home Insurance Claim in Tennessee: A Step-by-Step Guide for 2026 Asking your agent a coverage question is not the same as filing a claim: Asking your Tennessee home insurer a coverage question cannot, by itself, raise your premium or cancel your policy.
This article is informational only. It summarizes Tennessee statutes and is not legal advice. It does not promise coverage, eligibility, or any claim outcome; your policy forms and the facts of the loss control.
Related reading from All Seasons
- Tennessee law lists 15 unfair claims practices, including slow responses and unexplained claim denials.
- How to File a Home Insurance Claim in Tennessee: A Step-by-Step Guide for 2026
- How Tennesseans file an insurance complaint with TDCI’s Consumer Insurance Services.
- Storm Claim Underpaid in Tennessee? Your Next Steps
- Tennessee homeowners can cancel a roofing contract within three business days after their insurer says the claim is not covered.
- Asking your Tennessee home insurer a coverage question cannot, by itself, raise your premium or cancel your policy.
- TDCI explains Actual Cash Value versus Replacement Cost for Tennessee homeowners.
Free policy review
All Seasons Insurance Group offers a free personal policy review. Call 865-263-1400 or visit asigtn.com/get-a-quote/. This article is informational only and does not promise coverage or eligibility; your policy forms control. Seasons change. So should your coverage.
When does a Tennessee insurer have to give me a written statement of rights?
Tennessee Code § 56-7-125 requires it when you file a personal lines fire or homeowners claim for structural damage with an estimated value at or above $20,000.
Can I choose my own contractor on a Tennessee homeowners claim?
The required statement must tell you of your right to have repairs made by a contractor of your choice, hired by you, who does not work for or at the direction of the insurance company.
Can I get a copy of my homeowners policy for free?
Yes. The statement must advise you of the right to receive a copy of the insurance policy free of charge upon request.
What if my contractor disagrees with the insurer's estimate?
The statute says you have the right to a detailed estimate, and if your contractor has questions about it, you or your contractor should contact the claim representative directly.
Can I add damage after my first claim payment?
The statement must list your right to file supplemental claims as the need arises, such as when hidden damage is found during repairs.
What number do I call to file a complaint with the state?
The statute lists the Department's policyholder service section at 1-800-342-4029 if you cannot reach an agreement with the claim representative, agent, and company.
Why is my general contractor's name on my claim check?
Under Tennessee Code § 56-7-111, on losses over $1,000 the insurer must name the general contractor of any uncompleted construction or building contract as a payee on the draft.
How can All Seasons help after reading this?
Call 865-263-1400 or visit asigtn.com/get-a-quote/ for a free personal policy review. Informational only; no coverage promises. Seasons change. So should your coverage.